Every month I teach a startup workshop for the SBDC, and at some point, we talk about startup financing. I walk through the stages from my Funding Your Business Startup course because a founder’s funding options depend on where they are in the startup journey. Debt usually isn’t an option for an unproven startup, so the conversation turns to investors. Those investors could be you, friends and family, partners, or outside investors. Either way, investor money costs the founder something more permanent than interest. It costs ownership and control in the form of equity. So, the question in the room is always some version of the same thing: how much of my business do I have to give up?
I group the funding options into three stages. The Early-Stage is the bootstrap stage: the idea phase and a basic proof of concept. This stage is primarily for conducting research, and it’s not the time to bring in an investor. Next comes the Pre-Revenue stage, the equity/crowdfunding stage, where the work is product design and development. This stage often requires spending money to prove the idea. Since many small business founders don’t have deep pockets, it can make sense to bring in an early investor for a small equity stake. The last stage is the Profitable stage, the debt/factoring stage, where the business has proven its business and economic models with paying customers and is ready to scale.
How much equity you give up depends on how much risk you’ve removed by the time you ask. An early-stage idea with no proof of concept is the riskiest thing an investor can buy, which also makes it the cheapest. Sell equity too early, and you’re selling an interest in the business at the lowest price you’ll ever see. Even at the Pre-Revenue stage, with the concept proven but no sales yet, the price is still low compared to what it will be once the business is profitable. The way to raise that price isn’t a better pitch. It’s de-risking. And that idea isn’t only for people raising money. Whether it’s an investor’s money or more of your own going into the deal, you want to retire as much risk as possible before you make bigger bets. To explain what I mean, I tell the story of the Ship of Gold.
Why the Gold Had to Move
In the mid-1800s, gold was discovered in California. The problem was that, for all practical purposes, the United States still lived east of the Mississippi River. Going west overland meant crossing the river, which was treacherous. Then came the plains, where travelers ran into hostile encounters with Native Americans and desperados. Then came the Rocky Mountains, all before finally reaching the California coast.
And here’s the thing about gold. You can’t eat it. Gold is only useful when you trade it for something, and most miners needed what was available back East. So, the gold had to travel to the East Coast to buy goods, and those goods had to travel back to California. The transcontinental railroad hadn’t been built yet, so going across the country wasn’t a realistic option.
One option was a clipper ship sailing around the southern tip of South America, Cape Horn, and the surrounding Drake Passage. That was a long, dangerous trip, and those waters are known as a graveyard of ships.
The ingenious option was to split the journey. Steamships ran along each coast. A steamer carried the gold down the Pacific side to Panama, the Panama Railroad carried it across the isthmus, and another steamer carried it up the Atlantic side. The SS Central America handled that Atlantic leg, sailing via Havana to New York.
In September 1857, the SS Central America sailed into a hurricane off the coast of the Carolinas. Off parts of the East Coast, the continental shelf drops away fast, and that’s where she went down, taking about 425 lives and tons of gold with her into roughly 7,200 feet of water. That’s about a mile and a half down. In 1857, that meant the ship and her gold were gone forever.
The Modern Treasure Hunt in Three Rounds
Fast forward to the 1980s. In 1985, Bob Ballard found the Titanic, and deep-ocean exploration and recovery went from fantasy to an engineering problem. An Ohio ocean engineer named Tommy Thompson decided to try to recover the gold from the Central America, and he eventually built his own remotely operated submersible to do it.
A quick note before the numbers. The figures I use here are training numbers. I keep them simple so the math is easy to follow. If you want the real story of what each stage cost, read Gary Kinder’s Ship of Gold in the Deep Blue Sea.
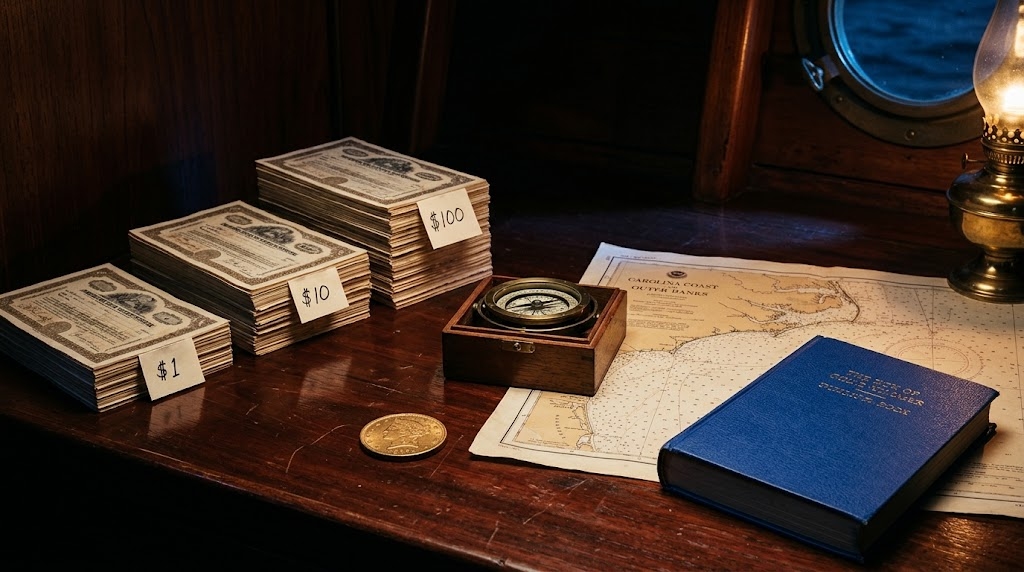
Round one was research. Thompson couldn’t afford to spend a year researching on his own dime, so he needed someone to cover his costs while he did. Call it $100,000. At that point, the venture was just an idea and a lot of risk, so he sold shares for $1 each until he’d sold 100,000 shares. He then spent about a year studying currents and weather, accounts from survivors and their families, and the ship’s last known positions. He returned with a probability map that narrowed the search to a likely area, but it was still far too vast to search with a submersible. That’s what set up round two.
Round two was locating the wreck. More than a mile down, you can’t see your hand in front of your face, and a submersible can only look at a tiny patch of the bottom at a time. The search area had to be narrowed before anyone sent one down. That meant hiring a ship to tow a side-scan sonar sled back and forth just above the ocean floor, looking for anomalies, at a cost of about $1,000,000. This time Thompson didn’t sell shares for $1. He sold them for $10. The sonar survey found a few anomalies on the bottom. One of them was probably the Central America.
Round three was confirming and recovering. Now the team needed a submersible to look at the anomaly, confirm it was the ship, and bring the gold to the surface. That cost about $10,000,000, and the shares now sold for $100 each.
This is usually where I stop in the workshop and ask the room a question. It’s the same share in the same venture. Why could Thompson get only $1 at the beginning, $10 in the middle, and $100 near the end? Nothing about the gold had changed. The risk had. That’s the whole point of de-risking the venture.
Why the Price Went Up Before Any Gold Came Up
When the third-round investors paid 100 times what the first-round investors paid, not a single coin had come off the ocean floor. The enterprise was worth more because the odds of success were higher.
Each round wasn’t really buying boats and equipment. It was buying an answer. Round one answered where the ship might be. Round two answered which spot on the bottom was worth looking at. Round three answered whether it was really the ship, and whether the gold could be recovered. Money buys evidence, evidence lowers risk, and lower risk raises value.
That’s why the price per share tracks perceived risk. The first money in takes the most risk, so it gets the most ownership for each dollar. Later money pays more because it’s buying a safer bet.
It also says something about where value comes from. An idea by itself has little value. Execution, and the proof it produces, is where real value is created.
For a founder, the consequence is simple. Sell equity before you’ve retired any risk, and you sell at the floor. Every stage you prove before you raise equity raises your share price and reduces how much of the business you have to give up.
The Same Rules Apply to Your Own Money
You may never sell shares to an outside investor. But many small businesses end up with partners, or friends and family, holding a piece of the business, and the same logic determines how much they should get. It even applies to borrowing. A lender also prices a loan based on risk, so the more risk you’ve retired before you ask, the less interest you’ll pay. And if no one else’s money is involved, the framework still applies. The treasure hunt’s three rounds ask the same three questions behind any new bet, whether it’s a new business, a new location, or a new service line.
Round one: is there anything down there? Before spending real money, find out whether the opportunity exists at all. Talk to the people who would buy, look at who’s already serving them, and test what you think you know. This round should be cheap.
Round two: where exactly? Narrow the big search box to a specific target: one customer type, one offer, one price. Run a small, real test before committing to the more expensive version. That might be a handful of jobs, a pre-sale, or a pilot with one customer.
Round three: confirm and recover. Once a cheaper stage proves demand, then and only then should you consider signing the lease, buying the truck, or hiring the crew. Don’t rent the $10,000,000 submersible before you’ve paid for the sonar.
At every stage, the same questions apply. What’s the riskiest unknown right now? What’s the cheapest way to answer it? What result earns the next, bigger commitment? And what result tells you to stop?
What AI Changed, and What It Didn’t
AI makes round-one work faster and cheaper than ever. That includes the research, the analysis, and even the first draft of a plan.
But it does that for everybody. When anyone can produce the same desk research in an afternoon, research stops being an advantage. Everyone shows up with it.
Moreover, AI research can be wrong. I’ve seen it produce false information. Research that hasn’t been tested isn’t evidence. It’s a more confident guess. The philosopher René Descartes made it his first rule “never to accept anything for true which I did not clearly know to be such.”
There’s an additional, quieter risk. If AI does all of the round-one research and you never internalize it yourself, everything that comes after gets messy. You’ll be making round-two and round-three decisions on findings you don’t truly understand. As with business planning, the journey is where a founder actually learns and internalizes the business. AI can speed up the trip, but it can’t take it for you.
So, AI shrinks round one, but it doesn’t skip round two. Thompson’s year of research only gave him a map of where the ship probably was. It took the sonar to find something real on the bottom. Today, a paying customer, a working prototype, or a signed vendor agreement is your sonar. That’s what raises your share price. A nicer research report doesn’t.
What the Rounds Look Like in Startup Funding
If you are raising outside money, the treasure hunt maps directly onto the three stages I described above. Each stage is really a risk-retirement stage, and each one has its own kind of money.
Seed Capital: The $1 Round
Seed capital pays for the Early-Stage: initial research, market validation, and a basic proof of concept. It’s the riskiest investment in a business’s life because, at this point, there’s nothing to buy but an idea and the founder’s commitment to it. This is where most of the research happens, much like the year Thompson spent figuring out where the ship might be, and it’s generally where the founder buys into the business with sweat equity, effectively at $1 a share.
Most of the work is legwork, and legwork doesn’t cost much in actual dollars. That’s why you should fund this stage yourself. It’s cheap. And at this level of risk, you can’t afford to give away equity, because you’d be selling it at the lowest price it will ever see. Thompson was the exception. He couldn’t afford a year of research, so he sold $1 shares to cover his costs, which is exactly why his first investors got their shares so cheaply. But notice that even with outside money paying for it, Thompson still did the work himself. Whoever funds this stage, the founder has to do the legwork. That’s how you come to really understand what you’re building.
I did exactly this when I started Horizon Interactive. I spent a year in the Early-Stage researching and writing the business plan, working with potential clients, and building the framing and momentum to move the project forward. I bought my shares for $1 each. When I brought in my two partners before we launched, I technically sold them shares at a considerably higher value than the $1 I’d paid. They were buying into a venture I had already de-risked.
Development Money: Series A and B, the $10 and $100 Rounds
Development money funds the Pre-Revenue stage. Like the sonar and the submersible, it pays to prove the idea and build toward the payoff. This is usually the first time the business has to spend real money rather than time, and the first time it might make sense to bring in an investor. Pre-Revenue development money typically comes in two rounds, each serving a different purpose.
Series A is about optimizing the idea. At this stage, the business generally has a business model, but it hasn’t yet proven its economic model. The job is to show the numbers hold up as it grows. In the treasure hunt, that’s the sonar: narrowing a large search area down to a few specific targets worth a closer look.
Series B is about developing the business. At this stage, the business generally hires key team members and builds a winning product. In the treasure hunt, that’s sending the submersible down to confirm the target and prepare to bring the gold up.
Each round costs more than the last, buys more evidence, and commands a higher price per share. The $10 investor is paying for the research that’s already been done. The $100 investor is paying for the sonar results too.
Scale Money: Series C and the Profitable Stage
Scale money funds the Profitable stage, and it’s the one stage the Ship of Gold story doesn’t cover, because I stop the story before the gold ever comes up. By now the market is proven, the product works, and customers are paying. The business has validated both its business model and its economic model, and it’s ready to scale manufacturing and distribution.
Series C is raising money to make money. It’s the least risky level of investment because the risk has been retired about as far as it can be. That changes the funding options too. Debt and factoring become available for the first time. Whether the expansion is funded with investor money or with debt, this is where share prices are highest and borrowing costs are lowest.
Every stock transaction carries a different level of risk and reward and should be priced accordingly. When you bring in a new investor or partner, the ownership you give up should match the risk remaining at the time of the offer, not the risk you had when you started.
What to Do Before You Give Up Equity
Start by knowing which stage you’re in. What risk is left in your venture right now?
Then ask whether you can fund the next stage without selling equity, using customers, vendors, or your own savings.